Writing / technology governance
Gold Loan Compliance Is a Data Problem
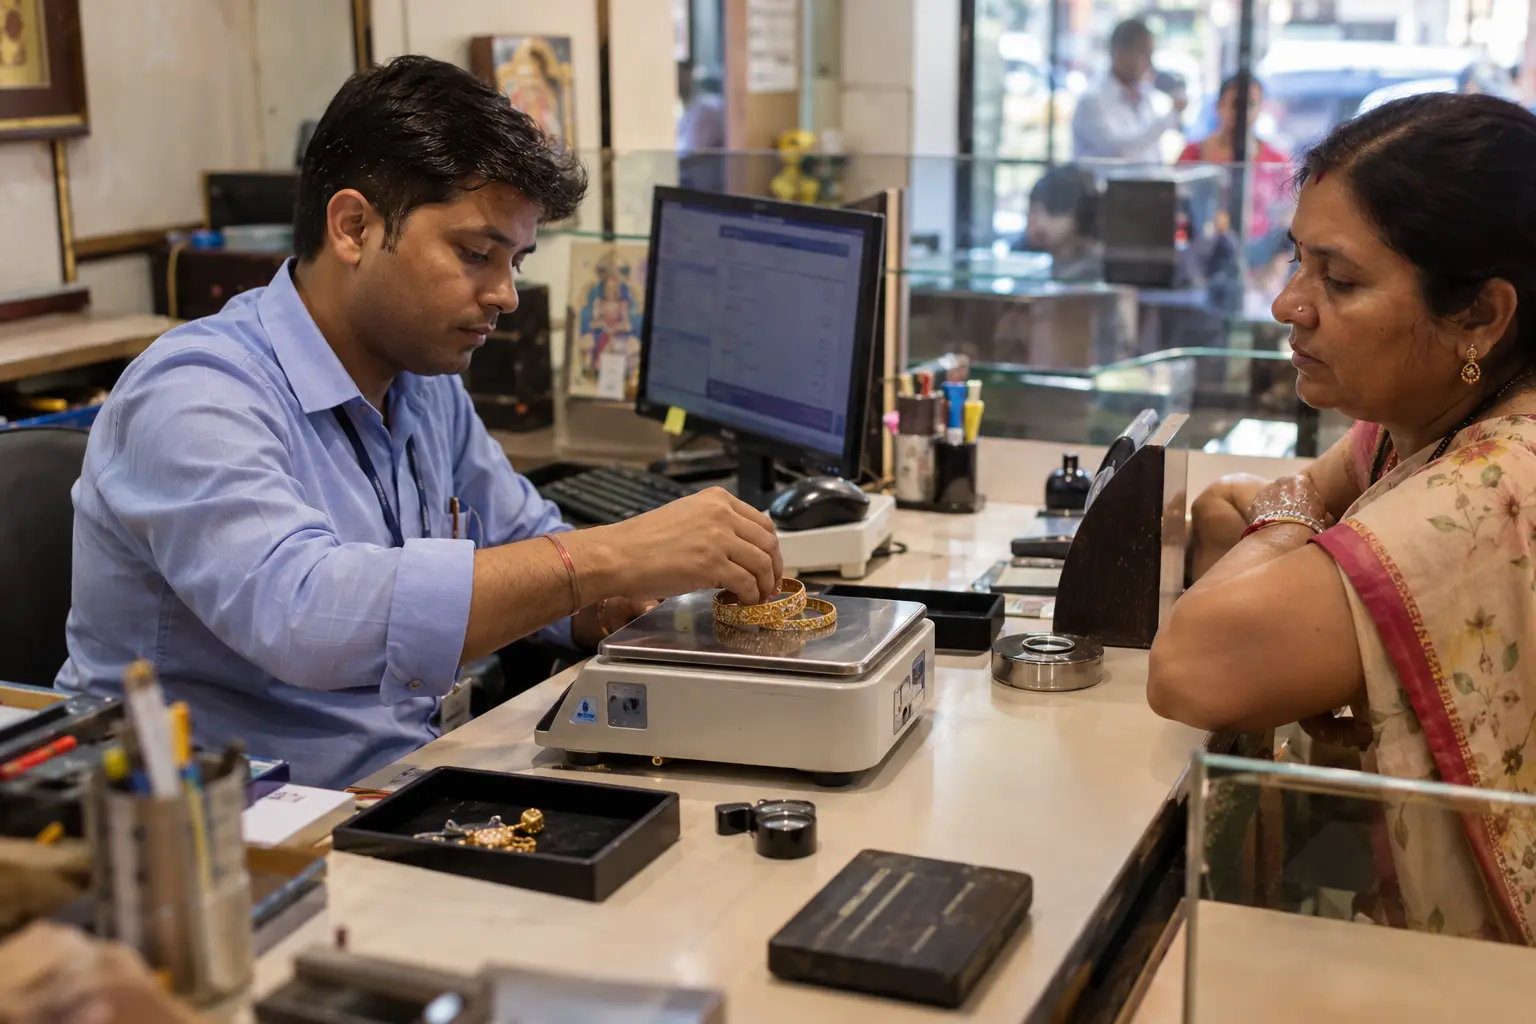
The Reserve Bank of India's directions on lending against gold and silver collateral had to be implemented by 1 April 2026. Most lenders treated them as a credit policy rewrite. My view is that the harder half of the work sits with technology, because almost every clause becomes a question a supervisor can ask about one specific loan on one specific day.
"Was this loan within its permitted loan-to-value ratio on the 14th?" "Which price did you use, and where did it come from?" "When was the gold returned after repayment?" A policy document cannot answer those questions. Only records can.
This piece is for CTOs, heads of lending operations and risk leaders at banks and NBFCs that lend against gold. It turns the directions into data requirements and shows where the evidence usually breaks.
The short version
The gold and silver lending directions harmonise rules across banks, co-operative banks and NBFCs. Their core obligations, from daily loan-to-value to release timelines, are provable only through timestamped system records. The unit of compliance is the loan-day, and your architecture should be designed around it.
- Compute loan-to-value daily for every live loan.
- Store the price used, its source and its date.
- Treat the assay certificate and image as tamper-evident evidence.
- Timestamp repayment and release against a working-day calendar.
- Flag renewals and top-ups in the system, not in remarks fields.
- Aggregate exposure per borrower across branches and loans.
This article sits inside the technology governance cluster, where the wider argument is set out in full.
Read the directions as data requirements
Take the text clause by clause and ask one question of each: what record would prove this happened?
- Loan-to-value. The directions define the ratio "on a day" and require it to be maintained throughout the tenor. That needs a daily calculation and a stored result.
- Valuation. Collateral is valued at the lower of the previous 30 days' average closing price and the previous day's closing price for that purity, published by the India Bullion and Jewellers Association or a SEBI-regulated commodity exchange. That needs a price feed with provenance.
- Assaying. The procedure must be standard across branches, done in the borrower's presence, and recorded in a certificate that includes purity, gross and net weight, deductions and an image of the collateral. That needs a structured, image-backed record.
- Renewals and top-ups. These must be clearly identifiable in the core banking or loan processing system. That needs a field, not a note.
- Release. Collateral must be returned on the day of full repayment and in any case within seven working days, with compensation of ₹5,000 per day for delays attributable to the lender. That needs event timestamps and a working-day calendar.
- Auction. Notices, a reserve price of at least 90 per cent of current value, and refund of any surplus within seven working days. That needs an auction ledger.
Read that list again and the pattern is clear. The regulator has described a data model. This article is general information, not legal advice on your obligations.
Loan-to-value is a daily calculation
Loan-to-value sounds like a number set at sanction. The directions make it a running measurement. Gold prices move every day, so a loan that was compliant at sanction can drift outside its limit without anyone touching it.
Three design details decide whether your calculation will stand up.
The price rule is a lower-of rule. Your engine needs both the 30-day average and the previous day's close for each purity, and it must pick the lower one. Store both values and the chosen one, with the publication source.
The limit depends on the borrower, not the loan. The maximum ratio is tiered by total consumption loan amount per borrower: 85 per cent up to ₹2.5 lakh, 80 per cent above that up to ₹5 lakh, and 75 per cent above ₹5 lakh. For bullet repayment loans the amount is the total payable at maturity. A borrower with three small loans at two branches may sit in a different tier from what any single loan suggests. You need a reliable customer identity across branches before you can calculate this correctly.
A breach needs a workflow. The lender's policy must say what happens when the ratio is exceeded. The system should create that task automatically and record how it was closed.
Should your organisation do this now?
- Yes, if loan-to-value is recalculated only at sanction or renewal.
- Not yet, if customers can hold loans under different identities across branches.
- Instead, first: clean up customer identity and link loans to one borrower record.
- Measure it by: share of live loans with a stored ratio for yesterday.
The assay record is evidence
Branch staff think of the assay certificate as paperwork. Treat it as the most important evidence the lender holds, because it is the only record of what was physically pledged.
The directions expect a standard assaying procedure used without deviation across every branch, the borrower present during assaying, and deductions for stones and fastenings explained and written into the certificate. They also require periodic surprise verification of pledged collateral, with records kept.
From a systems view, that means the certificate should be captured as structured fields plus an image, locked after sanction, and linked to every later event: surprise checks, release and auction. If a discrepancy appears at release, you want to compare two records made by the system, not two sheets of paper.
Risk: an image stored on a branch computer or a shared drive is not evidence. It is a file someone could replace.
Should your organisation do this now?
- Yes, if assay details or images live outside the loan system.
- Not yet, if branches lack the devices to capture images consistently.
- Instead, first: standardise capture hardware and the assay form.
- Measure it by: share of new loans with a locked, image-backed certificate.
Release and auction run on timestamps
The seven-working-day release window and the ₹5,000 daily compensation turn a service promise into a measurable liability. You cannot manage that liability without two timestamps per loan: when full repayment was received, and when the collateral was handed back and verified against the certificate.
Working days also need a calendar. A national holiday list is not enough if branches observe different local holidays.
The auction side works the same way. You need a record of the notice and its acknowledgement, the reserve price calculated with the same valuation rule, the amount realised, and the surplus refund date. Each is a timestamped event. Together they are the answer to a borrower complaint.
Should your organisation do this now?
- Yes, if release dates are recorded manually or not at all.
- Not yet, if repayment posting itself runs a day late.
- Instead, first: make repayment posting real time or same day.
- Measure it by: share of releases within seven working days, by branch.
A simple test for your architecture
Here is a test I would run before calling the programme finished. Pick ten closed loans at random from different branches and ask the team to answer, from system records alone and without phoning a branch:
- What was the ratio on any date I name, and which price produced it?
- Who assayed the collateral, and where is the image?
- Was the borrower present, and how is that recorded?
- Was this a renewal or a top-up, and was it within the permitted ratio?
- When was the loan repaid and when was the gold released?
- If it went to auction, what was the reserve price and when was the surplus refunded?
Every answer that needs a phone call is a gap. Count them. That count is a more honest measure of readiness than any policy sign-off.
Before you approve it
Checklist for the programme:
- Daily loan-to-value engine with stored inputs and results.
- Price feed with source, purity and publication date retained.
- Single borrower identity across branches and products.
- Locked, image-backed assay certificates linked to later events.
- Repayment and release timestamps against a branch-aware calendar.
- System flags for renewals and top-ups.
- Auction ledger covering notice, reserve price, proceeds and refund.
Questions to ask:
- Your team: can we recreate yesterday's ratio for any loan without a spreadsheet?
- Your team: how many borrowers hold loans at more than one branch?
- Your LMS vendor: where is the price source stored, and can it be edited after the fact?
- Your LMS vendor: is the assay image immutable once the loan is sanctioned?
- Your board: what did compensation for delayed release cost last quarter?
- Your board: which branches fail the ten-loan test?
How to measure it
- Daily ratio coverage. Share of live loans with a stored ratio for the previous day. Baseline: current state. Owner: head of lending technology. Review: weekly. Leading.
- Breach closure time. Days from a ratio breach to documented action. Baseline: last 90 days. Owner: credit risk. Review: monthly. Leading.
- Evidence-backed certificates. Share of new loans with a locked certificate and image. Baseline: last quarter. Owner: branch operations. Review: monthly. Leading.
- Release timeliness. Share of releases within seven working days, by branch. Baseline: last quarter. Owner: operations head. Review: monthly. Lagging.
- Compensation paid. Rupees paid for delayed release. Baseline: last two quarters. Owner: CFO. Review: quarterly. Lagging.
- Ten-loan test gaps. Answers needing a phone call. Baseline: first test. Owner: internal audit. Review: quarterly. Leading.
Mistakes that cost the most
Calculating the ratio per loan instead of per borrower
The tier depends on total exposure to the borrower.
- Why it happens: loan systems were built around accounts, not people.
- Prevention: aggregate by a verified customer identity.
- Early warning: the same person appearing under slightly different names.
Storing the ratio but not the price
A number without its input cannot be defended.
- Why it happens: storage was once expensive and prices were "known".
- Prevention: store both candidate prices, the chosen one and the source.
- Early warning: auditors asking where a valuation came from.
Allowing edits after sanction
Editable assay records invite disputes and suspicion.
- Why it happens: branches need to fix typing errors.
- Prevention: corrections as new, approved records, never overwrites.
- Early warning: certificate changes made days after sanction.
Recording release on paper
The seven-day window then becomes impossible to prove.
- Why it happens: release happens at the counter, far from the system.
- Prevention: a release step in the loan system with borrower acknowledgement.
- Early warning: closed loans with no release date.
Treating top-ups as fresh loans
The directions require renewals and top-ups to be identifiable.
- Why it happens: creating a new loan is easier than modifying one.
- Prevention: a mandatory loan type flag with validation rules.
- Early warning: borrowers with frequent short loans on the same collateral.
Frequently asked questions
When did RBI's gold loan directions apply?
The directions were issued on 6 June 2025 and required compliance no later than 1 April 2026. Loans sanctioned before a lender adopted them continue under the earlier rules.
Who do the directions cover?
Commercial banks including small finance and regional rural banks, primary and rural co-operative banks, and all NBFCs including housing finance companies, for loans where gold or silver jewellery, ornaments or coins are accepted as collateral.
What are the maximum loan-to-value ratios?
For consumption loans, 85 per cent where total loans per borrower are up to ₹2.5 lakh, 80 per cent above ₹2.5 lakh up to ₹5 lakh, and 75 per cent above ₹5 lakh. The ratio must be maintained throughout the loan.
Which gold price should a lender use?
The lower of the previous 30 days' average closing price and the previous day's closing price for that purity, as published by the India Bullion and Jewellers Association or a SEBI-regulated commodity exchange.
How quickly must gold be returned after repayment?
On the same day where possible and within seven working days at most. Where the delay is attributable to the lender, compensation is ₹5,000 for each day beyond that limit.
Do stones in jewellery count towards value?
No. Only the intrinsic value of the gold or silver content is counted. Stones and other cost elements are excluded.
What must the assay certificate include?
Purity, gross weight, net weight, deductions for stones and fastenings, any damage noticed, an image of the collateral and its value at sanction. One copy goes to the borrower.
What happens to unclaimed gold?
Collateral lying with the lender for more than two years after full repayment is treated as unclaimed. Lenders must run drives to trace borrowers and report to the board or customer service committee every six months.
What to do next
Run the ten-loan test this month and share the gap count with your risk committee. For how the same evidence logic applies to incident reporting, read the six-hour test for NBFC cyber directions, and see the technology governance topic page for the wider framework.
Sources
- Reserve Bank of India, Lending Against Gold and Silver Collateral Directions, 2025, 6 June 2025, updated 29 September 2025. rbi.org.in
Last reviewed: 15 September 2026.
Views are my own and do not represent my employer.
This article is general information, not legal advice.